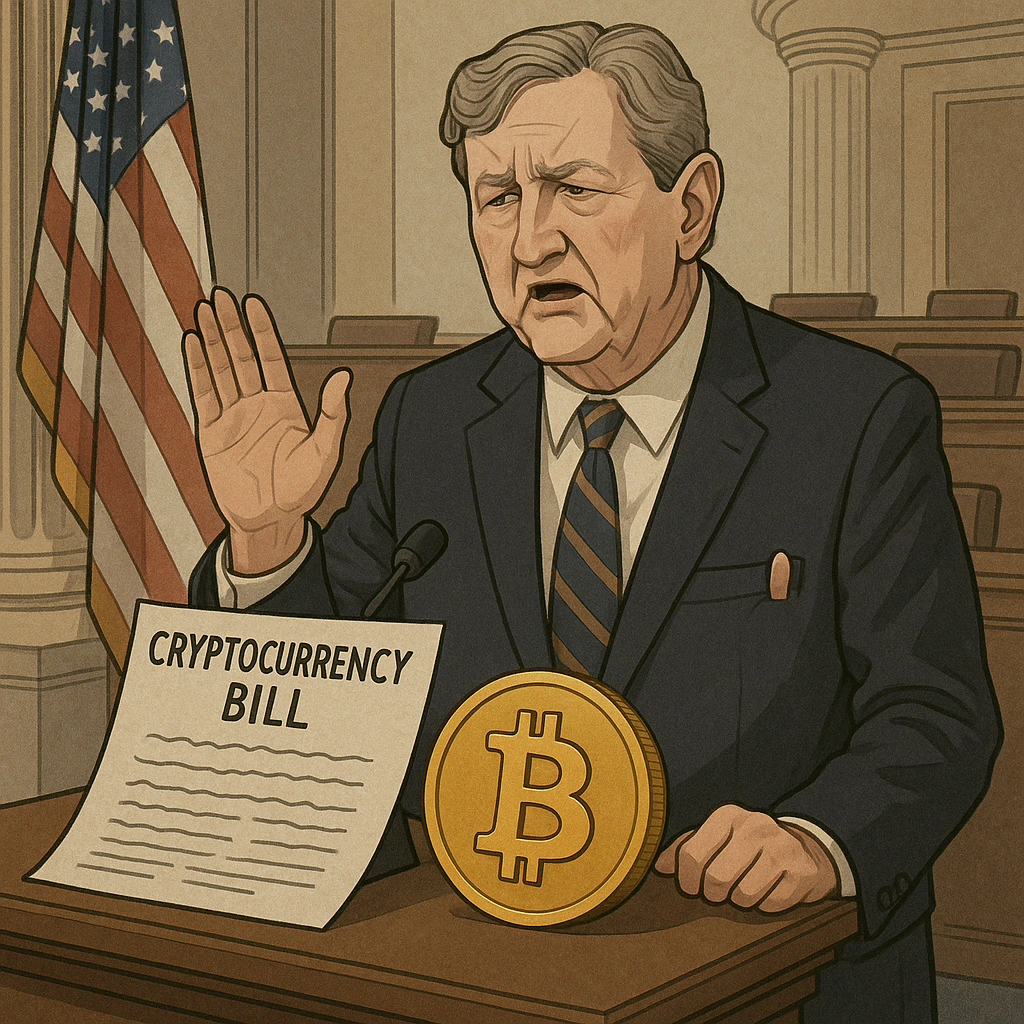
Efforts to push forward a landmark cryptocurrency regulation bill in the U.S. Senate have hit turbulence, with Republican lawmakers divided over how quickly to proceed.
Kennedy Pushes Back on September Timeline
On Wednesday, Sen. John Kennedy (R-La.), a senior member of the Senate Banking Committee, said he does not believe the committee is prepared to move ahead with the proposed legislation. His comments put into question Sen. Tim Scott’s (R-S.C.) plan to hold a markup session before September ends.
“I don’t think we’re ready,” Kennedy told reporters, noting that both lawmakers and outside experts still had unresolved concerns. His remarks are the clearest sign yet of resistance from within Republican ranks.
Kennedy has long cautioned against rushing crypto regulation, arguing that the draft bill could grant the digital asset industry too much influence. The proposal aims to split oversight responsibilities between the Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC)—a major structural change to U.S. financial regulation.
Scott’s Push for Market Structure Bill
Sen. Scott, who serves as the Banking Committee’s ranking Republican, has been a vocal advocate for moving the legislation forward. His office emphasized that the framework has been months in the making, with input from more than 160 stakeholders and thousands of pages of feedback.
“The House has already acted, and the Senate should not fall behind,” Scott’s spokesperson Jeff Naft said, referring to the House-passed CLARITY Act.
Republicans also introduced the GENIUS Act earlier this summer to establish clearer rules for dollar-pegged stablecoins. But Kennedy dismissed that effort as only a “baby step” compared to the more comprehensive market structure overhaul now under debate.
Framework and Industry Pressure
In June, Scott joined Senators Cynthia Lummis (R-Wyo.), Thom Tillis (R-N.C.), and Bill Hagerty (R-Tenn.) in releasing a set of principles for digital asset oversight. Their blueprint called for clearer boundaries between securities and commodities, joint supervision by the SEC and CFTC, and anti-money laundering provisions designed to support innovation while protecting consumers.
Crypto executives have strongly backed the push. Coinbase CEO Brian Armstrong called the effort “a clear path forward,” while Andreessen Horowitz’s Colin McCune argued that comprehensive regulation has been “sorely needed for years.” The industry has poured hundreds of millions of dollars into lobbying to secure regulatory clarity.
Bipartisan Challenges
Still, skepticism isn’t confined to Republicans. Sen. Andy Kim (D-N.J.), a Democrat on the Banking Committee, echoed concerns, saying it would be a “mistake” to rush a markup this month. Other Democrats, though open to the idea of regulation, have also urged caution.
The disagreement leaves Scott’s September 30 deadline in doubt. He had previously declared the target “realistic,” warning that the U.S. risks falling behind the European Union and Singapore, both of which already have digital asset frameworks in place.
Democrats Counter With Their Own Proposal
The outlook for the CLARITY Act has grown even murkier after a group of 12 Senate Democrats unveiled their own crypto regulatory proposal on September 9. Their framework emphasized stricter disclosure rules, mandatory platform registration with the Financial Crimes Enforcement Network (FinCEN), and expanded SEC and CFTC authority.
Notably, the Democratic plan also sought to reduce political conflicts of interest by banning lawmakers and their families from profiting from cryptocurrency holdings.
At the SALT Wyoming Blockchain Symposium in August, Scott had predicted that as many as two-thirds of Senate Democrats might back the GOP plan. But with the release of the rival Democratic bill, expectations have shifted sharply.
On prediction market Polymarket, the odds of the CLARITY Act becoming law in 2025 have dropped to just 32%, down from nearly 90% in July.
Get the weekly commit
New blockchain deep dives every week.
